The IRS makes most nonprofits file an annual Form 990, and it is one of the best things that ever happened to people who like nonprofit data. Want to know how much an organization takes in? Look at the 990. How much does it spend? Look at the 990. Who sits on the board? Look at the 990. How much is the CEO paid?
Yep, the CEO’s compensation shows up on the Form 990. You have no idea what the CEO of your local grocery store or plumbing supply store makes, but you can find out what the CEO of your local nonprofit makes. Go to Candid or ProPublica and search for it.
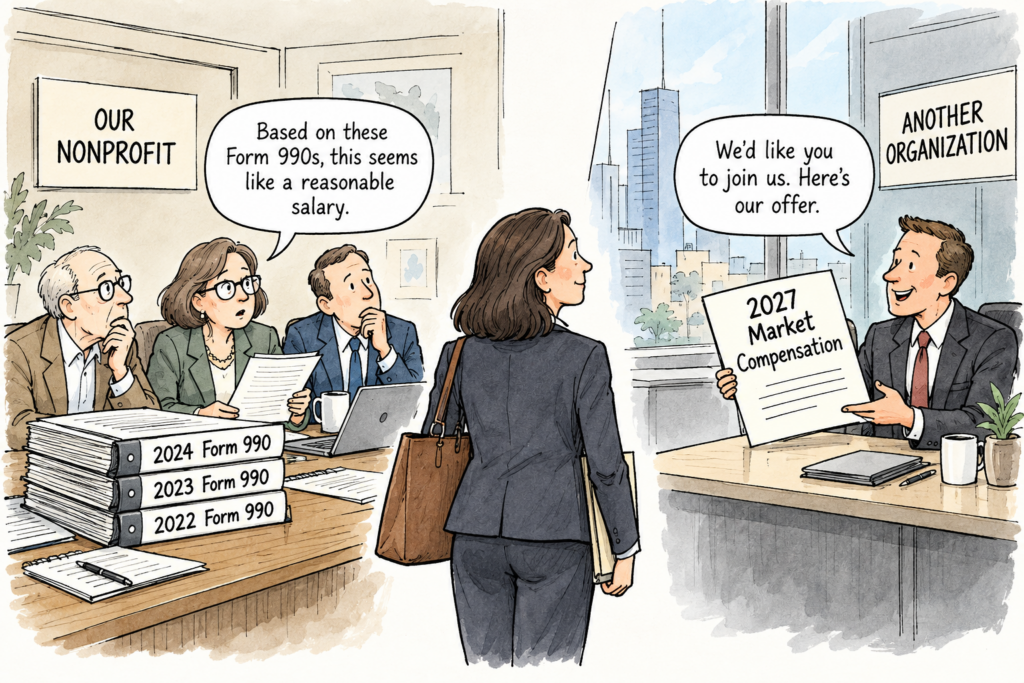
The problem is that a Form 990 can look considerably more current than the information inside it actually is. The latest 990 probably doesn’t tell you what the CEO is earning – it tells you what they were earning in the past. If you are setting the CEO’s compensation based on what the 990s from similar organizations show, you are basing your decision on historical data, not the current market.
First, there is the filing delay
A nonprofit does not file its Form 990 the day its fiscal year ends. The return generally isn’t due until the 15th day of the fifth month afterward. And an organization can obtain an automatic six-month extension.
For example, take a nonprofit operating on a calendar year. Its 2025 fiscal year ended on December 31, 2025. Its Form 990 normally isn’t due until May 15, 2026. With an extension, it may not be filed until roughly mid-November 2026.
By the time you see the number, it may reflect compensation set a year or more earlier, and the CEO may already have received one or even two subsequent adjustments. Nobody is doing anything shady or sneaky – it’s just that the numbers reported are from the past, not the present.
Then there is the deceptively simple year on the form
This part can be legitimately confusing.
Suppose an organization has a fiscal year running from July 1, 2025 through June 30, 2026. You might reasonably call that its “2026 fiscal year.” The IRS, however, tells the organization to use the 2025 Form 990, because its fiscal year began in 2025.
Look carefully at the top of the form and you will see the actual dates:
Tax year beginning July 1, 2025 and ending June 30, 2026.
So a Form 990 with 2025 printed prominently on it may actually contain financial information through the middle of 2026.
Confused yet?
I’m just getting warmed up.
CEO compensation can come from still another period
For organizations with fiscal years, executive compensation reported in Part VII generally does not follow the fiscal year. The IRS requires the organization to report that compensation for the calendar year ending within the fiscal year.
Return to our nonprofit with the July 1, 2025 through June 30, 2026 fiscal year.
You’ll find that the revenues and expenses generally cover those twelve months. But the CEO compensation shown in Part VII comes from calendar year 2025.
So we can have one document with three dates attached to it:
2025 Form 990
Fiscal year ending June 30, 2026
CEO compensation for calendar year 2025
And depending upon when the organization files, you may not be looking at that information until late 2026 or even 2027 through one of the public databases people commonly use for nonprofit research. Suddenly the nice clean number in the CEO compensation column doesn’t seem quite current at all, because it isn’t.
That doesn’t make Form 990 data bad
I rely heavily on Form 990 data in compensation reviews. It is extraordinarily useful because it gives us standardized information about thousands of nonprofit organizations that would otherwise be difficult or impossible to obtain.
But I don’t think a board should confuse the most recent publicly available number with the current market rate. Those aren’t really the same thing.
If you are looking at comparable organizations to help establish reasonable CEO compensation, check the actual fiscal period covered by each return. Check which calendar year the compensation represents. Look at several organizations rather than one or two. And recognize that a salary reported on the newest 990 you can find may describe a compensation decision made a year or two ago.
Then consider what has happened since: inflation, salary adjustments, changes in the organization, changes in the CEO’s responsibilities and changes in the market for nonprofit executives.
Form 990 provides valuable evidence, but when you’re using it to judge the compensation market, you’re looking through a rear-view mirror. Losing a good CEO because your compensation data was looking backward can cost an organization a lot of time, money and disruption. None of that advances the mission the board is there to protect.